The World’s Most Exclusive Credit Cards
Most exclusive cards sit on a spectrum: operational benefits on one end, pure status on the other.
If you manage a team with a £3m annual budget, a concierge saves operational friction. If you earn six figures but use the card twice yearly, you’re paying for prestige.
The cards that deliver a measurable Return on Investment (ROI) and the ones that sell status at a premium are not the same list.
1. American Express Centurion Card, the Most Famous Credit Card
If American Express invites you, the Centurion is a by-invitation-only charge card that signals wealth and commitment to one issuer. At $10,000 to join, it also carries the highest published fee of any card on this list.
The real decision: is the initiation fee and annual cost worth the operational concierge layer and community access? Most cardholders subsidise status, not benefits.
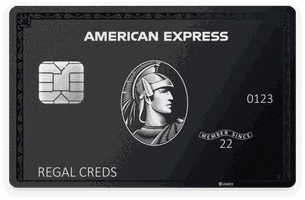
The card features a sleek black anodised-titanium design: exclusivity marketing designed to make you feel part of an exclusive club.
Benefits and Rewards
- Personal Concierge, Your dedicated concierge handles restaurant reservations, travel planning, and event sourcing. If you travel 50+ times a year and your time costs more than £100/hour, this saves money. If you travel 5 times yearly, you’re paying roughly £500 per trip for this layer.
- Elite Status with Travel Partners, Automatic upgrades and lounge access through hotel chains, airlines, and car rental partners. Lounge access is not what sets the card apart, because Coutts Silk includes LoungeKey access with no annual fee. Most of the Centurion’s fee pays for the status and the service layer rather than the lounges.
- Exclusive Events, Invitation-only events (fashion shows, premieres, private parties). Matters if you entertain clients or value network access. For most cardholders, it’s a benefit you hear about but rarely use.
- Premium Travel Insurance, Coverage includes medical emergencies, trip cancellations, and lost luggage. Every premium card at this level offers this, so it does nothing to set the Centurion apart.
Fee Structure and Requirements
Upfront cost: a $10,000 initiation fee plus $5,000 a year, per American Express’s US Centurion cardmember agreement (June 2025). Year-one total: $15,000.
American Express does not publish a spend threshold. Centurion membership is by invitation only, and in the US a form to register interest is not an application for credit.
2. JP Morgan Reserve Card, the Most Luxurious Credit Card
If you bank with J.P. Morgan’s private bank, the Reserve is the travel card that comes with that relationship. J.P. Morgan publishes almost nothing about it, so its benefits can only be judged second-hand, from what card review sites report.
That also rules out a fair comparison on published terms. We can set out Citi Prestige’s 4th-night hotel credit further down this page, but we cannot put the Reserve’s own terms beside it, because J.P. Morgan has not published them.
The design features palladium and 23-karat gold accents, so you get the recognition without the Centurion’s $10,000 joining fee.
Benefits and Rewards
- Published terms, J.P. Morgan publishes no rewards or benefit terms for the Reserve on a public page, so we cannot confirm a sign-up bonus, earn rate or travel credit for it.
- What reports say, Card review sites report that its earning rates, annual credits and lounge access now match the Chase Sapphire Reserve, whose terms Chase publishes. That is the closest public guide, not the Reserve’s own terms.
Fee Structure and Requirements
Annual cost: J.P. Morgan does not publish the fee. Card comparison sites list it at $795 a year, and one says some long-standing holders are still on about $550.
The card goes by invitation to J.P. Morgan Private Bank clients, and J.P. Morgan does not publish the asset level it asks for. Without that relationship, you can’t apply.
3. Dubai First Royale Mastercard, the Most Secret Credit Card
If you’re Gulf-based with existing Dubai First relationships, this card offers operational advantages. If you’re reading this in the UK, you won’t get an invitation.
We found almost no public detail about this card; fees are undisclosed. That opacity is intentional: it signals you’re in a tier above public credit cards.
The design features a gold border, signalling a price most people would rather not have to think about.
Benefits and Rewards
- No Spending Limit, Dubai First publishes no spending limit for the card, and reports describe it as having none. If you need this feature, you already have it on other cards. If you don’t, it’s meaningless.
- Relationship Manager, Dedicated manager available 24/7 to handle travel, dining, and logistics. Genuinely useful if you travel constantly and need someone managing the operational layer.
- Event Access, Access to fashion shows, premieres, and VIP events. We noted the other invitation-only cards open much the same doors.
- Lounge Access & Transfers, Complimentary airport lounge access and luxury transfers (likely private car to/from airport) reduce travel friction. If you fly often, this is the perk you will use most.
- Lifestyle Benefits, Preferential hotel rates, golf memberships, and exclusive dining access. Real perks for someone living a luxury lifestyle.
Fee Structure and Requirements
Annual fee: not publicly disclosed.
Invitation-only for Dubai First clients with substantial assets. Direct application not available.
4. Coutts Silk Card, the Most Elegant Credit Card
If you bank with Coutts, the Silk is the most accessible exclusive card. Coutts’s own joining page, which we read in October 2026, asks new clients to hold at least £3m in investments or savings with it, or borrow at least £3m, within three months.
You earn points and get lounge access with no annual fee, against the Centurion’s $10,000 joining fee. Next to Citi Prestige, Silk charges no fee where Prestige did, and Prestige no longer takes applicants.
The design is elegant and understated: positioned for subtle wealth, not ostentatious status.
Benefits and Rewards
- Reward Points, Earn Coutts Crowns on every pound spent, redeemable for travel, dining, and experiences. The points are worth having and will not decide anything: Silk carries no annual fee, so they are a bonus on spending you would do anyway.
- Lounge Access, LoungeKey access to over 1,100 executive lounges in over 300 airports, with a £24 entry fee per person. Entry is not free, so count the fee if you fly often.
- Travel Insurance, Not part of the card. Coutts sells Coutts Travel Protection to Private Current Account holders: free with over £1m of combined assets or liabilities at Coutts, £400 a year below that.
Fee Structure and Requirements
Annual cost: no annual fee for Coutts clients aged 18 or over. Coutts’s Silk Card page, read in October 2026, says the card comes as part of its standard quarterly banking tariff, so the cost sits in what you already pay to bank there.
Available to Coutts private clients only, with the credit limit set by Coutts’s own credit assessment. This is the most accessible card on this list if you meet the banking requirement.
5. Stratus Rewards Visa, the Most Experience-Focused Credit Card
Stratus Rewards sold luxury experiences rather than operational benefits: private jet time, yacht charters and VIP events in place of lounges and hotel points. Members paid for community and curation, not for the points system.
It is also the hardest card here to pin down today. American Banker reported in March 2010 that U.S. Bancorp, which issued the card from 2004, stopped issuing it in 2006, and that a European version was planned with its fees still being settled. We could not find a current issuer page for it, so this entry describes what the White Card offered, not a card anyone is known to issue now.
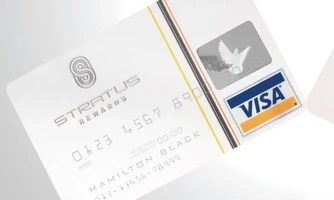
The design was white, hence the name: exclusivity without the gold-and-titanium theatre.
Benefits and Rewards
- Stratus Points, Members earned points on spending, and the points went on luxury travel. That was the whole reason to prefer Stratus, and of no use to anyone who wanted hotel points.
- Private Jet & Yacht Redemptions, Where airline miles buy seats, Stratus points bought private jet time and yacht charters.
- Event Access, Red-carpet premieres, VIP sporting events, and private fashion shows. The other invitation-only cards on this list open similar doors, though Stratus marketed events as a core benefit.
- Concierge, A 24/7 concierge arranged travel and dining, as it does on every card at this price.
Fee Structure and Requirements
Annual cost: no current fee to quote. When U.S. Bank launched the card in 2004, Chief Marketer reported $1,500 a year for the main card and $500 for a second one, and American Banker gave the same figures in 2010.
Membership came through one of Stratus’s partners or by nomination from an existing member, never by public application.
6. Citi Prestige Card, the Most Accessible Honest Premium Card
Citi Prestige was the only card on this list that a member of the public could simply apply for, in the US, with published terms and no initiation fee, which made it the easiest of the seven to judge on value. Citi closed it to new applicants in July 2021, so existing holders are the only people who still carry it.
Its 4th-night hotel credit is the benefit that set it apart from the other travel cards here, though it pays out at most twice a year.
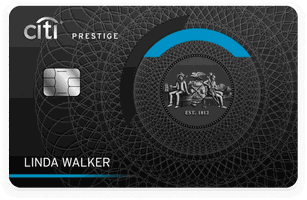
The design is elegant and accessible, and that positioning is deliberate.
Benefits and Rewards
- ThankYou Points, Earn Citi ThankYou Points on spending, redeemable for travel, dining, and shopping. The earn rate is unremarkable, so the points are not the reason to hold it.
- 4th Night Free, The headline benefit. The fourth night is complimentary on stays of four or more consecutive nights booked through Citi Travel, and only twice a year. At two uses a year, it is worth two hotel nights at most.
- Lounge Access, Priority Pass Select covers 1,300+ lounges. The lounge access is the same Priority Pass most premium cards bundle, so it is not a reason to choose this one.
- Concierge, 24/7 concierge handles bookings and reservations, though every card at this tier offers the same.
- Travel Insurance, Medical, trip cancellation, and baggage coverage. Standard inclusion.
- Event Access, Wine tastings and sporting events. Worth having, and only if you entertain.
Fee Structure and Requirements
Annual cost: no current fee to quote. Citi closed the card to new applicants in July 2021.
Citi publishes no income threshold for the card, and with applications closed there is no route to approval for a new reader.
7. Merrill Lynch Octave Black Card, the Card for Constant International Travelers
Merrill no longer offers the Octave, so this entry shows what a wealth-manager travel card used to include rather than a card you can still get. It went to Merrill Lynch wealth management clients with no initiation fee, and it paid uncapped points, lounge access and a $350 annual travel credit against a $950 annual fee, as card review sites recorded it while the card was on sale.
We set it against Citi Prestige, and the Octave had nothing to match Prestige’s 4th-night hotel credit. Both cards are now closed to new applicants, so the comparison only matters to someone who already holds one of them.
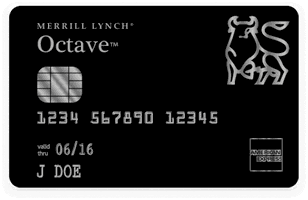
The design was plain black, which suited a card built to be used on the road rather than shown off.
Benefits and Rewards
- Uncapped Points, US Credit Card Guide recorded 2.5 Merrill points per dollar on all purchases, with no cap.
- Annual Travel Credit, The same review site recorded a $350 annual travel credit, or a Delta Sky Club membership in its place. Against the $950 annual fee it also recorded, the credit covered just over a third of the cost.
- No Foreign Transaction Fee, The review site recorded no foreign transaction fee, which mattered more than it sounds on a card used mainly abroad.
Fee Structure and Requirements
Annual cost: no current fee to quote. US Credit Card Guide, which recorded the card’s terms while it was on sale, says it no longer accepts new applications, and gives its annual fee as $950.
There is no route to the card for a new reader.
Opening: The Reality Behind Exclusive Cards
These cards promise extraordinary perks. But extraordinary fees, invitation-only status, and limited practical utility mean almost nobody reading this will ever hold one.
The useful question isn’t “Is this good?” but “For whom?” A $5,000 annual fee on top of a $10,000 joining fee is absurd for a salaried employee. For someone spending $500,000 yearly on business travel, it might resolve operational friction. For someone earning six figures but rarely using the card, it subsidises pure status.
Most people paying £1,000+ annually subsidise status, not benefits. For the right person (a wealth manager handling ultra-high-net-worth clients, a business traveller with rigid patterns, someone with genuine operational friction), the fee resolves real problems. For everyone else, it’s a subscription to prestige.
Which Exclusive Cards Can UK Readers Actually Get?
Most accessible: Coutts Silk Card (if you bank with Coutts, which asks clients to hold or borrow at least £3m).
No longer available: Citi Prestige (closed to new applicants in July 2021; it was a US card), Merrill Lynch Octave (no longer accepting applications) and Stratus Rewards (its US issuer stopped issuing it in 2006).
Effectively unavailable: Amex Centurion, JP Morgan Reserve and Dubai First Royale.
Unless you bank with Coutts, the world’s most exclusive cards are simply not built with you in mind.
Best Cards for Frequent Travellers
Best overall travel ROI: Coutts Silk, the only card here a new reader can still get with published terms and no annual fee. Citi Prestige was the open-application alternative until it closed to new applicants in July 2021.
Best lounge access: Coutts Silk is the only card here that publishes its lounge terms: over 1,100 lounges, with a £24 entry fee per person.
Best for pure status: Amex Centurion (concierge and brand recognition, but at premium cost).
Card Status vs. Benefits: What You’re Actually Paying For
Amex Centurion and Dubai First Royale deliver genuine status if that matters to you. But the US Centurion costs $5,000 a year after a $10,000 joining fee, and Dubai First does not publish its fee, for a distinction that lasts until someone else shows a darker card.
The operational benefits (concierge, lounge access) are real, but lounge access doesn’t need a $5,000 card: Coutts Silk includes it with no annual fee, at £24 a visit.
Coutts Silk is the honest choice: it carries no annual fee and its benefits are published, though you must bank with Coutts first. Citi Prestige filled the same role until it closed to new applicants in July 2021. Amex Centurion and Dubai First are aspirational choices. They work if you’re paying for access to a community and a service layer that status-only cards don’t provide.
Frequently Asked Questions
What’s the difference between an exclusive credit card and a regular premium card?
Exclusive cards are invitation-only with ultra-high spending requirements and often unavailable to the general public. They target ultra-high-net-worth individuals, and most issuers publish no wealth or spend threshold. Regular premium cards have application processes open to the public with published eligibility criteria.
Can I apply for these cards, or are they truly invitation-only?
Most are purely invitation-only (Amex Centurion, JP Morgan, Dubai First Royale), and Merrill Lynch no longer offers the Octave. Coutts Silk needs no separate invitation, but only Coutts private clients can have one. Stratus Rewards admitted members through a partner or by nomination from an existing member, and its US issuer stopped issuing the card in 2006. Citi Prestige closed to new applicants in July 2021. Spending history with existing cards often matters more than income alone.
Do these cards actually deliver value, or is the fee pure status?
Value depends entirely on your lifestyle and spending patterns. A frequent business traveller might justify $1k annual fees through lounge access and travel credits. Casual spenders paying $500+ annually for cards they rarely use are subsidising pure status. The math only works if you use the benefits actively.
Which exclusive credit card is best for UK readers?
For UK readers: Coutts Silk Card (if you bank with Coutts) is the most accessible and practical. Citi Prestige closed to new applicants in July 2021 and was a US card, so it is not an option for UK readers. Amex Centurion and JP Morgan Reserve are effectively unreachable without existing relationships and massive spending history. Dubai First Royale is region-locked outside its market, and Merrill Lynch no longer offers the Octave.
How we reviewed The 7 Most Exclusive Credit Cards in the World
Ranking criteria. We assessed each card on fee structure, eligibility, UK accessibility, and the measurable value of its stated benefits. Access and real cost carry the most weight because they determine who this card is actually for.
Data sources. Two issuers publish terms we could read: American Express (its US Centurion cardmember agreement) and Coutts (its Silk Card and joining pages), both last read on 6 October 2026. J.P. Morgan and Dubai First publish no terms we could find, and Citi, Merrill and Stratus no longer offer their cards, so those entries rest on press and card review sites, named where the page uses them. We re-read those sources on 2 November 2026, except for Dubai First, whose entry was last checked on 23 April 2026.
Update cadence. This page has no fixed re-check schedule. The date at the top covers the Coutts and American Express terms only; the other cards carry the dates given above. Some links on this page are affiliate links; see our editorial policy.
Regulatory note. This page is editorial content, not regulated financial advice. Credit products are subject to status and approval, and none of the cards here takes an application from the general public in the UK.