Business Expert is an independent comparison site. Some partners may compensate us for promotion. This never affects our impartial evaluations based on fees, customer service, and product features.
Best Card Machines for Small Businesses (2026)
Square Reader suits most small businesses: £19, a flat 1.75%, no contract. Once card takings pass £2,500 a month, Tide gets cheaper.
Best Card Machines for Small Businesses at a Glance
This guide ranks card machines on how well they do the job. If your first question is what the thing costs to buy and run, start with the cheapest card machines, where we cost every option against turnover and average sale.
Fees verified against each provider’s own UK pricing page, 21 July 2026. Rates shown are for UK consumer cards taken in person unless stated; Amex, commercial, overseas and online cards can cost more. TakePayments and Barclaycard quote individually. The fees section below sets out which card types carry a different rate at each provider.
Best Card Machines for Small Businesses
The right pick depends on how you trade, which is why we ranked them that way. You take a busy Saturday afternoon of card sales, then spend Monday morning waiting for the money to reach your account, and that gap is where settlement speed earns its place.
A customer stands at your counter on a Friday afternoon while the reader keeps trying to reconnect, and the queue behind them grows. Connectivity is the difference between a sale and a walkout.
We ranked these by the decision most likely to cost you money if you get it wrong. Each pick below
answers a specific business question: what’s your volume, how do you trade, and what breaks if
settlement is slow? Every category includes an explicit condition for when that pick is the wrong call.
Best Overall
Square Reader costs £19 plus VAT, with no monthly fee or contract. Its 1.75% in-person rate applies to UK-issued cards, including Amex, and the free Square Point of Sale app covers basic sales, products and reporting.
It is not the lowest rate here. It is the best starting point because the cost is predictable and there is little commitment if the business changes direction. Square also supports offline payments for up to 24 hours, subject to its conditions, which gives it more resilience than a basic phone-paired reader that simply stops when the connection drops.
Square becomes less attractive once turnover is high enough to justify a paid plan. On Tide’s £17.99-plus-VAT Essential plan, the 0.89% plus 3p rate can cost less at around £3,000 a month in card sales for a non-VAT-registered business with a £20 average transaction. Hardware changes the first-year break-even point, so use your own figures before switching.
Not right if: you can already forecast consistently higher card turnover, or you need a standalone 4G terminal rather than a reader paired with a phone or tablet.
Tide Sell In-Person has three plans, with domestic consumer debit fees quoted ex VAT: Pay As You Go has no monthly fee, charges 1.5% plus 5p and settles in two to three working days; Essential costs £17.99 a month, charges 0.89% plus 3p, settles in two to three working days and can be cancelled at any time. Premium costs £19.99 a month or £159.99 annually, charges 0.69% plus 3p and includes next-day settlement on a 12-month contract.
The reader requires a Tide business account, so this is also a banking decision. The plan is most convincing when you already want Tide and can maintain enough card turnover to justify the fixed monthly charge.
Tide does not accept Amex. A business serving corporate travellers, premium retail customers or other groups that use Amex regularly should include the lost or redirected sales in its decision, not just the fee percentage.
Not right if: your turnover is low or irregular, you do not want to move banking to Tide, or Amex is important to your customers.
myPOS Go 2 costs £39 and includes its own 4G connection. It does not depend on a phone, which makes it a better fit for markets, mobile services and sites where Bluetooth pairing is inconvenient.
Payments settle immediately into a myPOS e-money account. You then transfer the money to your usual business account if you want it elsewhere.
The 1.10% plus 7p rate applies to UK consumer cards. Amex costs 2.45% plus 7p, EEA cards 2.20% plus 7p and other commercial cards 2.85% plus 7p. A business with a mixed card profile may therefore pay considerably more than the headline rate.
Not right if: you trade from a stable fixed checkout, or you take enough Amex, overseas or commercial cards to lose the advantage of the domestic rate.
Tyl by NatWest offers countertop and portable terminals from £13.99 plus VAT a month. Its 1.39% plus 5p rate covers UK and European personal cards; other cards cost more.
Funds can reach NatWest, RBS and Ulster Bank accounts on the same day, with next-working-day settlement to other banks. The combination of a conventional terminal and bank settlement makes Tyl a sensible fit for an established shop that wants equipment kept at a fixed location.
The contract runs for 12 months. Price the full term at the standard rental, even if a temporary free-hardware offer is available when you apply.
Not right if: you trade seasonally, move between locations, or do not want a hardware rental commitment.
Dojo charges a 1.2% blended transaction rate for businesses taking less than £100,000 a year by card. Hardware is separate: the Go Max costs from £149 upfront or £25 a month, while other terminals have their own purchase or rental price. Its Essential software is free; Plus costs £11.99 a month per location.
A blended rate is useful in hospitality because the price does not rise when a customer uses Amex or a commercial card. Dojo also integrates with more than 450 EPOS systems, and its Pocket terminal supports table ordering and split bills.
The 1.2% rate is lower than Square’s 1.75%, but that does not make Dojo cheaper for every business. The terminal cost must be recovered from the percentage saving. A £15 monthly rental alone requires about £2,730 of card turnover before the 0.55 percentage-point saving over Square covers it; a £25 rental raises that point to about £4,550. Any additional charges in the quote also need to be included.
Not right if: your monthly card volume is too low to recover the hardware cost, or you want one simple price without separate equipment and software decisions.
Zettle by PayPal settles card payments to a PayPal balance in minutes. The reader costs £29 excluding VAT, in-person payments cost 1.75% and there is no monthly fee or fixed contract.
This is most useful for a business already receiving online payments through PayPal. In-person and online takings arrive in one balance, which can simplify reconciliation.
The speed claim applies to the PayPal balance. Moving the money to another business bank account is a separate step and may take longer.
Not right if: you need the takings to arrive directly in your bank account without passing through PayPal.
SumUp Solo Lite costs £25 and charges 1.69% per in-person payment without a subscription. SumUp’s Payments Plus plan reduces the domestic consumer-card rate to 0.99% for £19 a month.
The paid plan begins to cover its subscription at roughly £2,715 of monthly card sales. Below that, pay as you go costs less. Above it, the lower percentage can save money, provided most payments qualify for the 0.99% rate.
SumUp also offers standalone terminals when a business no longer wants to rely on a phone. That lets a small operation change equipment and pricing without changing payment provider.
Not right if: you already use Tide or Revolut and can obtain a lower rate inside an account you need anyway.
Barclaycard Smartpay Anywhere costs £29 plus VAT and has no monthly fee, minimum volume or fixed contract. Settlement is normally the next working day and may be earlier for Barclays customers.
Barclaycard no longer publishes a standard transaction percentage for this reader. You need a quote, which makes it impossible to rank on price until the rate and card-class charges are known.
Smartpay Anywhere accepts Visa and Mastercard but not Amex. Other Barclaycard terminals do accept Amex under their own quoted rates.
Not right if: you want to compare a published rate before applying, or you need to accept Amex.
The original Revolut Reader is discontinued. New customers can buy the Lite Terminal for £129 plus VAT or the Terminal for £169 plus VAT. Both require a Revolut Business account, which starts at £10 a month.
The published in-person rate starts at 0.8% plus 2p for domestic consumer cards. Amex costs 1.7% plus 2p, while international and commercial cards cost more. Takings settle into a Revolut Merchant account and are usually ready to pay out within 24 hours, after which you move them into your Business balance.
This is a credible add-on if you already pay for Revolut Business and use its expense or multi-currency tools. It is not a cheap standalone reader once the account fee and current hardware price are included.
Not right if: you do not already want Revolut Business, or you need settlement into a different bank without another transfer.
Not ideal if: High-volume sellers who would benefit from Dojo or other negotiated per-transaction rates
Transaction fee1.75% flat (all cards incl. Amex)
Monthly feeNone
Hardware cost£19 +VAT
SettlementNext working day (1–2 days standard)
ContractNo lock-in
Amex acceptedYes: same 1.75% rate
Eligibility: UK businesses: sole traders, partnerships, and limited companies. Account holders must be 18 or over. Custom rates available for businesses processing over £200,000 annually. Prohibited categories include firearms and other restricted activities: see Square’s Acceptable Use Policy.
Not ideal if: High-volume sellers who would benefit from Dojo or other negotiated per-transaction rates
Best for: Sole traders and startups wanting the lowest hardware entry cost
Watch out: Battery degrades in cold weather and Bluetooth fails if phone dies mid-shift
Not ideal if: Businesses expecting to scale past £5,000/month quickly, a plan switch will be needed
Transaction fee1.69% in-person flat (0.99% on Payments Plus plan)
Monthly fee£0 or £19/month (Payments Plus)
Hardware cost£25
SettlementNext day
ContractNo contract
Amex acceptedYes, in-person only, at the standard flat rate
Not ideal if: Businesses expecting to scale past £5,000/month quickly, a plan switch will be needed
Watch out: Battery degrades in cold weather and Bluetooth fails if phone dies mid-shift
£25 hardware price is one of the lowest entry points on the market
Next-day settlement is faster than Square’s standard 1–2 working days
Payments Plus at 0.99% is a credible upgrade path above £4,000/month
Amex accepted in-person at the flat rate, no separate premium-card policy needed
Hardware battery degrades in cold weather, unreliable on winter outdoor markets
Bluetooth-to-phone fails if the phone dies on a busy shift
Payments Plus break-even is £3,800/month, most small users should not subscribe
Online/payment-link transactions cost 2.5%, well above the 1.69% in-person rate
SumUp Solo Lite reader at £25 (formerly branded SumUp Air), pairs with the free SumUp app on iOS and Android
Free SumUp POS app, sales reports, item library, basic inventory and team management included with no subscription
Next-day settlement on every plan, or instant payout to a SumUp business account at no extra cost
Payments Plus subscription at £19/month drops the in-person transaction rate to 0.99%, best for businesses processing above £3,300/month
Accepts all major debit and credit cards including Amex in-person at the standard flat rate; online/payment-link transactions are charged 2.5%
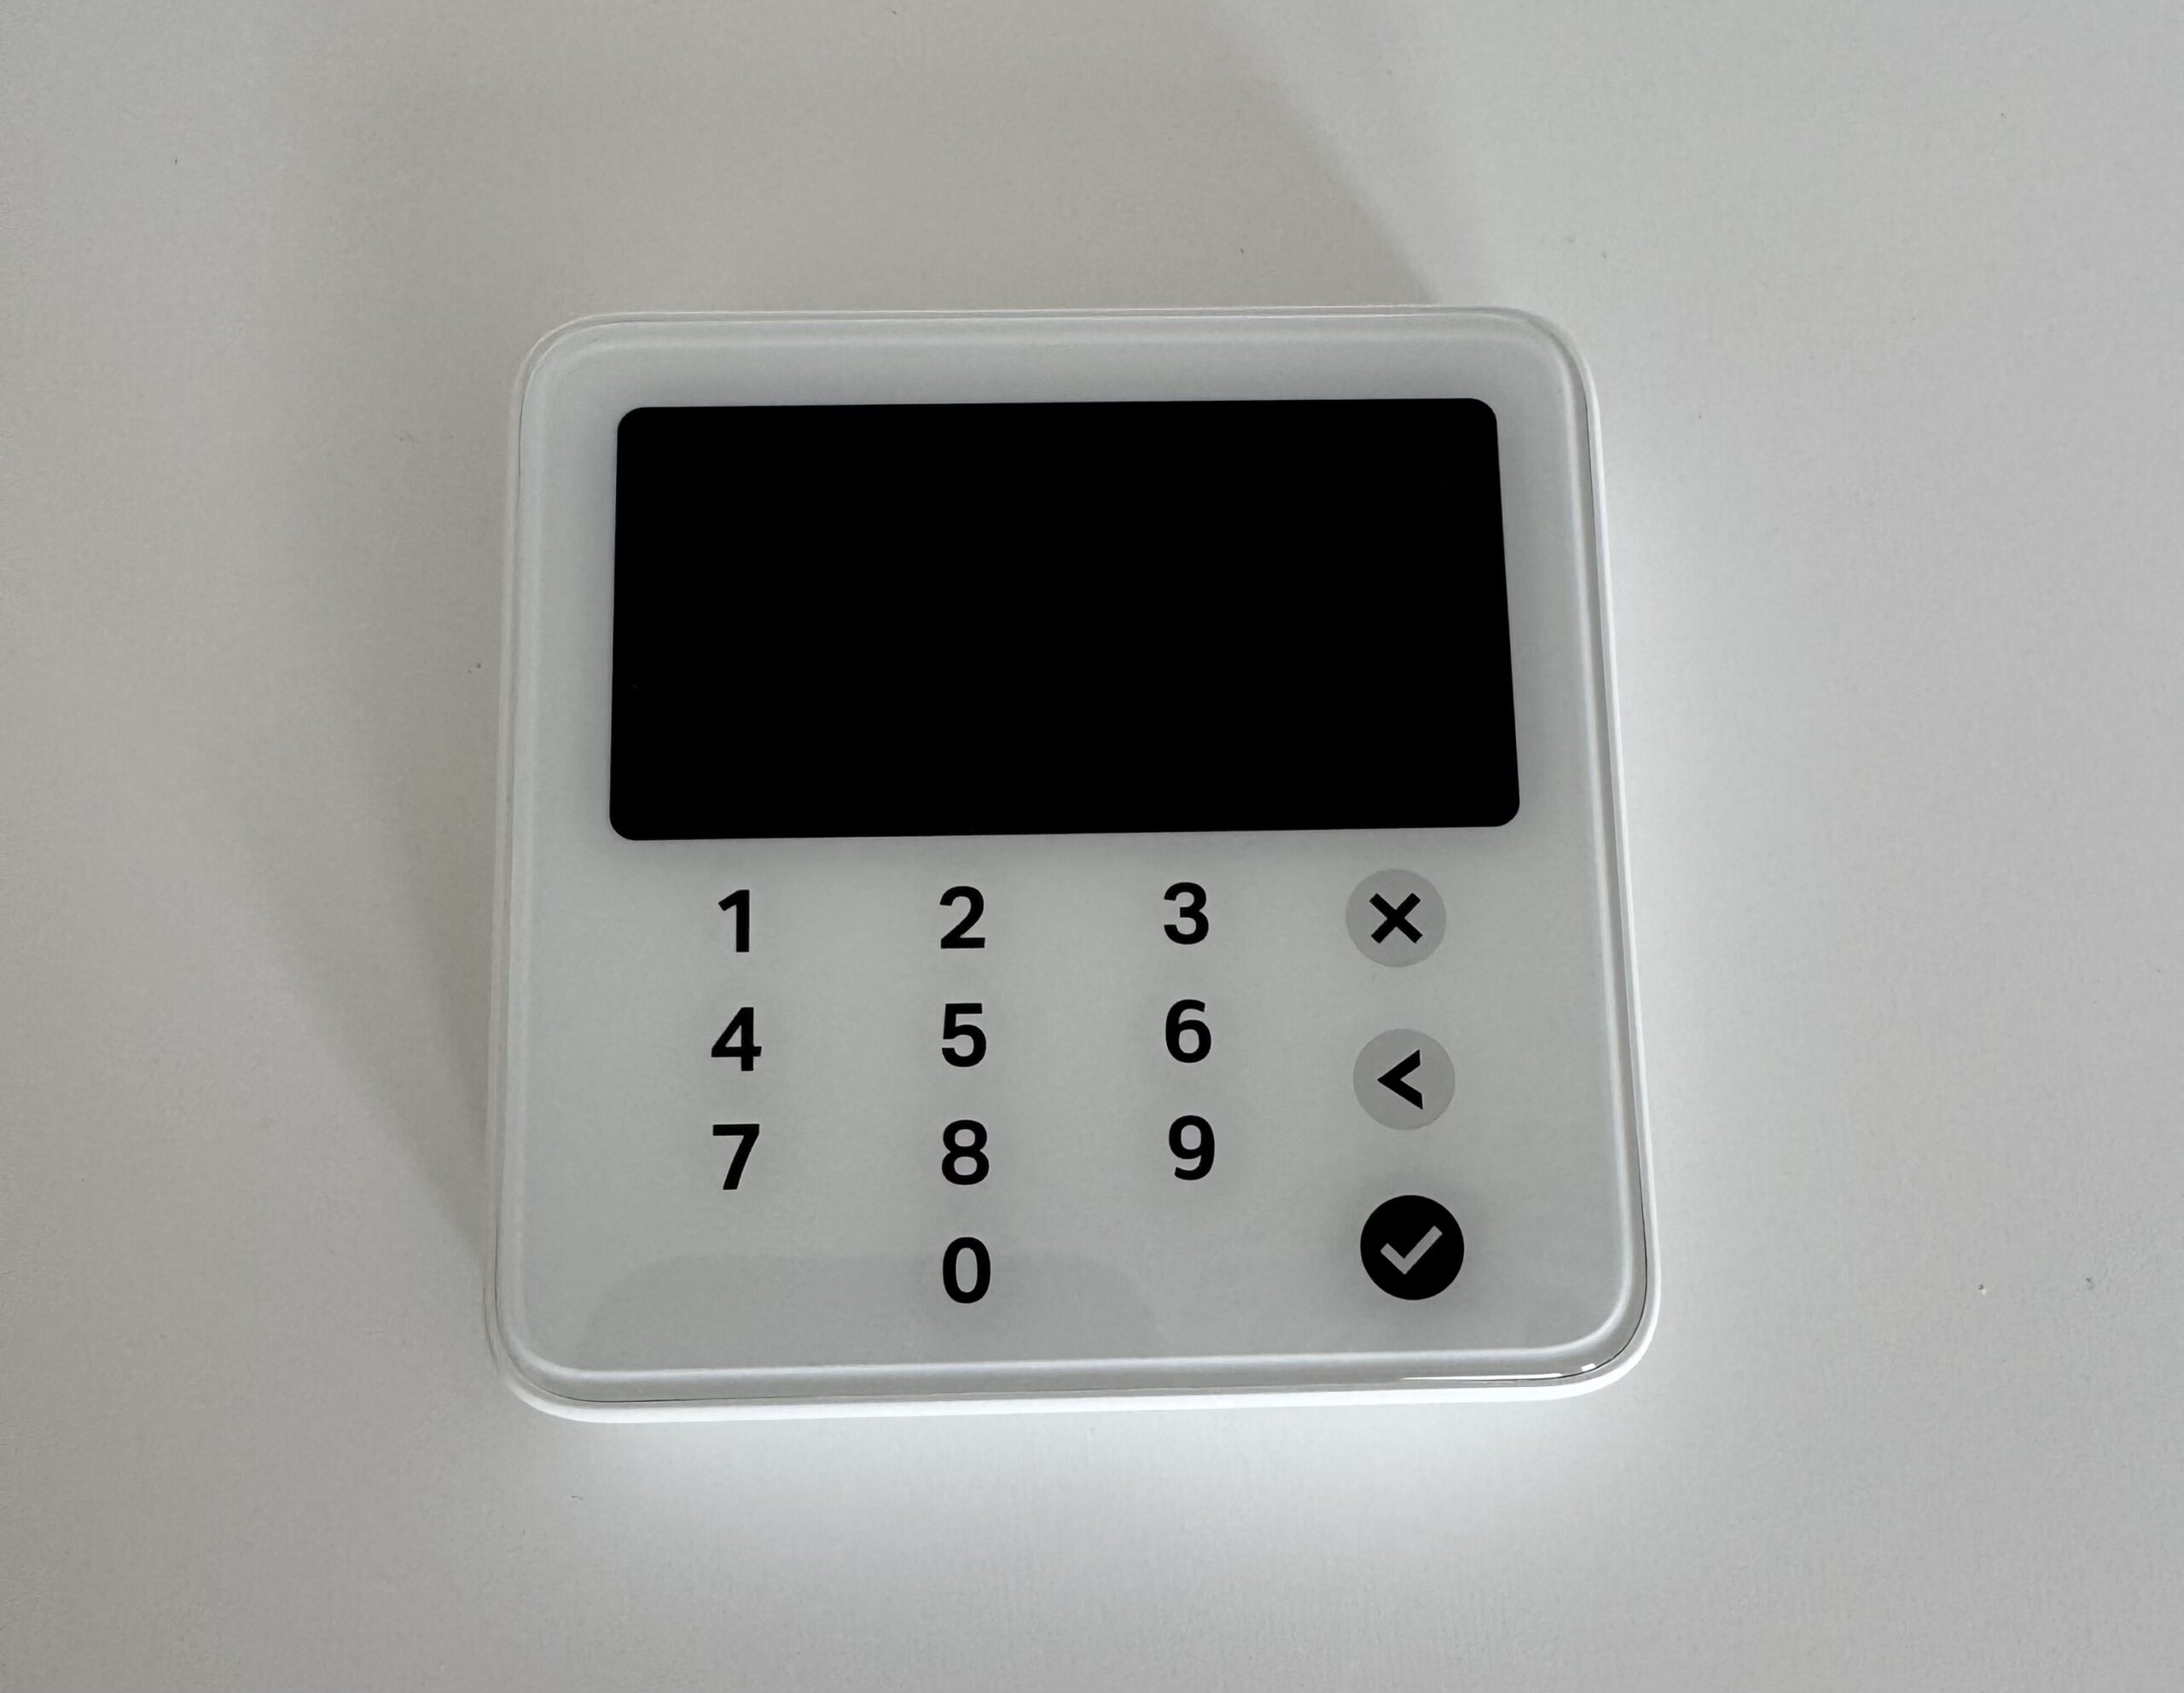
The SumUp Solo Lite we handled, front-on. It is the cheapest way onto SumUp, a phone-paired reader with no screen of its own, which is why it is the start-up pick here rather than the reader for a busy counter.
myPOS Go 2
Best for Mobile
Best for Mobile
myPOS Go 2
The right choice for any mobile business where “no signal” means “no payment”.
Best for: Existing Revolut Business users wanting low in-person rates without a long-term contract
Watch out: Revolut Business account required, minimum £10/month plan on top of hardware cost
Not ideal if: Businesses that need certainty on Amex terms before ordering; the Reader’s current Amex acceptance and rate aren’t clearly published, confirm directly first
Transaction feeFrom 0.8% + £0.02 (all plans)
Monthly feeFrom £10/month (Revolut Business account required)
Hardware costDiscontinued (was £49 +VAT)
SettlementNext day (24h, incl. weekends)
ContractNo contract
Amex acceptedNo (Reader); Yes on Terminal and Gateway
Eligibility: Revolut Business account required. Sole-trader eligibility is unresolved in Revolut’s own sources (its Business Terms include new sole traders, its Help Centre lists them as unsupported). Limited companies, partnerships supported. Business must be UK-registered, operate in supported industries.
Not ideal if: Businesses that need certainty on Amex terms before ordering; the Reader’s current Amex acceptance and rate aren’t clearly published, confirm directly first
Watch out: Revolut Business account required, minimum £10/month plan on top of hardware cost
From 0.8% + £0.02 is among the lowest in-person rates without a rental contract
No separate contract, stop using the reader any time with no penalty
Takings are usually ready to pay out from your Revolut Merchant account within 24 hours of each sale
Amex terms for the Reader specifically aren’t clearly published, confirm before relying on it for Amex-heavy trade
Revolut Business account required at a minimum £10/month
Commercial and international cards cost 2.6% + 2p, above the 0.8% consumer headline
From 0.8% + 2p, among the lowest in-person rates available without a rental contract
Revolut Pay activates in one click for any merchant already using Stripe
Terminal model (£169 +VAT) adds 4G eSIM, Amex and Revolut Pay support
Settles into a Revolut Merchant account alongside your Business account, usually within 24 hours
Tide Card Reader
Low-fee option
Low-fee option
Tide Card Reader
The cheapest reader that comes with a full business account, if you can live without Amex and bank with Tide.
Best for: Tide business account holders taking regular in-person payments. Tide says its Sell In-Person plans save money above £2,900 a month in card payments
Watch out: No Amex acceptance and a 2-3 working day standard settlement are hard stops for many businesses
Not ideal if: Businesses whose customers regularly pay by Amex, or any business not banking with Tide
Transaction fee1.5% + 5p pay as you go / 0.89% + 3p Essential / 0.69% + 3p Premium
Monthly fee£0 PAYG or £17.99 +VAT/month (Sell In-Person plan)
Hardware costNano from £11 +VAT; Card Reader £29 to £49 +VAT; Card Reader Plus £49 to £69 +VAT, by plan
Settlement2-3 working days; next day on Premium or £2.99 +VAT/month add-on
ContractTide business account required
Amex acceptedNo
Not ideal if: Businesses whose customers regularly pay by Amex, or any business not banking with Tide
Watch out: No Amex acceptance and a 2-3 working day standard settlement are hard stops for many businesses
Sell In-Person Premium at 0.69% + 3p is the lowest in-person rate in this guide, and it comes bundled with a full business account
The Card Reader and Card Reader Plus carry a free lifetime 4G connection, so neither needs a phone or WiFi to take a payment
Settles directly into the Tide account, one balance, one reconciliation
£59 introductory hardware price undercuts most rental alternatives
No Amex acceptance, a hard stop for hospitality, salons, and premium retail
Requires a Tide business account, which means a bank switch for most applicants
Standard settlement takes 2-3 working days unless you pay for Premium or the next-day add-on
0.89% + 3p on Sell In-Person Essential and 0.69% + 3p on Premium, among the lowest rates in this guide for mid-volume sellers
Card Reader and Card Reader Plus have free lifetime 4G built in, and switch between WiFi and mobile data on their own
Settles directly to Tide business account, single balance, no transfer step
Three hardware models: Nano (uses your phone), Card Reader (4″ display, email receipts) and Card Reader Plus (5.5″, paper receipts)
Dojo Go Max
Best for Hospitality
Best for Hospitality
Dojo Go Max
Dojo has moved away from its old flat-fee Fix plan to a 1.2% blended rate below £100k annual turnover, with hardware and software priced separately.
Best for: Hospitality and retail businesses that want a single blended processing rate rather than a monthly-fee-plus-percentage structure, with strong EPOS integration. Dojo Pocket suits table-service hospitality (pay at table, split bills).
Watch out: The current 1.2% blended rate applies to businesses under £100k annual card turnover; above that, the rate is a custom quote, not a published figure. The old £39.99/month Fix plan is no longer on Dojo’s public pricing page.
Not ideal if: Businesses that want transaction fees and hardware bundled into one number, or that need same-day (not next-day) settlement.
Transaction fee1.2% blended rate (all cards, under £100k annual turnover), plus £0.05 per authorisation
Refund fee£0.50 per refund
Software feeEssential free; Plus £11.99/month/location
Hardware costFrom £15/month (Wired) to £25/month (Go Max), or upfront from £149
SettlementNext day
ContractNot itemised for sub-£100k tier; £3,000 contract buyout offered
Amex acceptedYes, included in the blended rate
Eligibility: UK businesses, described as serving 100,000+ businesses. Pricing tier is set by annual card turnover: under £100k, £100k+, and £5m+.
Not ideal if: Businesses that want transaction fees and hardware bundled into one number, or that need same-day (not next-day) settlement.
Watch out: The current 1.2% blended rate applies to businesses under £100k annual card turnover; above that, the rate is a custom quote, not a published figure. The old £39.99/month Fix plan is no longer on Dojo’s public pricing page.
1.2% blended rate applies to every card transaction below £100k annual turnover: one number to budget against, no card-class tiers to track
Hardware priced separately with launch-offer discounts: Go Max at £149 upfront (was £229)
Dojo Pocket handles orders, tipping and split bills at the table, no third-party app needed
Contract buyout up to £3,000 removes switching friction if locked into a contract elsewhere
450+ EPOS integrations covering most major hospitality and retail systems
The 1.2% blended rate is quote-eligibility gated at £100k annual turnover; above that, pricing is a custom quote, not published
£0.05 per-authorisation fee and £0.50 per-refund fee (per Dojo’s FAQ) add up on high-volume, small-ticket trade
Software features beyond the basics (customer analytics, remote refunds) sit behind the £11.99/month Plus plan
Settlement is next-day, not the same-day some competitors advertise
Public pricing page does not itemise a card-class breakdown (Amex, EEA, commercial) the way some competitors do
1.2% all-in blended transaction rate for businesses under £100k annual card turnover
Dojo Pocket for table-side ordering, tipping and split bills
Integrates with 450+ EPOS systems
Contract buyout up to £3,000 for switching from another provider
Revenue-based business advances via Dojo Flex Funds
Takepayments
Bespoke pricing
Bespoke pricing
Takepayments
Worth a call once you are doing enough volume to negotiate, not before.
Best for: Market stalls, mobile traders, pop-ups, and small retail or food businesses wanting zero monthly fees and no contracts. The Zettle Terminal is the strongest mobile hardware pick in the UK due to built-in 4G at no ongoing cost.
Watch out: Money lands in PayPal first: one extra transfer step before cash reaches your bank account
Not ideal if: Businesses wanting settlement direct to a bank account: PayPal transfer step adds a day to cash position
Transaction fee1.75% flat (all cards incl. Amex)
Monthly feeNone
Hardware cost£29 +VAT (Reader 2); £149 +VAT (Terminal with 4G)
SettlementMinutes to PayPal; 1–2 days to bank account
ContractNo contract
Amex acceptedYes
Not ideal if: Businesses wanting settlement direct to a bank account: PayPal transfer step adds a day to cash position
Watch out: Money lands in PayPal first: one extra transfer step before cash reaches your bank account
Minutes-to-account settlement into PayPal: the fastest non-myPOS option here
1.75% flat including Amex: matches Square on the in-person rate
Useful for businesses with an existing PayPal invoicing or e-commerce flow
Money sits in PayPal, not a business bank account: one more transfer step before cash is usable
POS app is thinner than Square’s: fine for simple retail, weaker for hospitality
No volume discount structure exists
Zettle Go free POS app: item library, inventory tracking, sales reports and team management included at no extra cost
Instant PayPal settlement: funds available in your PayPal balance immediately after each transaction, no working-day delay
Hardware range from the £29 Zettle Reader 2 to the Zettle Terminal with built-in receipt printer: flexible setup for any counter
PayPal-integrated checkout: customers can pay via PayPal QR at the till, and PayPal online transactions feed into the same merchant account
Built-in product variants, discounts and gift cards: works for retail, hospitality and service businesses out of the box without add-on subscriptions
Barclaycard Smartpay Anywhere
Bank-grade acquirer
Bank-grade acquirer
Barclaycard Smartpay Anywhere
Worth considering once turnover crosses six figures and you want a bank-grade acquirer without committing to rental.
ContractHistorically 18 months; reconfirm current term at quote
Amex acceptedYes
Not ideal if: Sole traders and small businesses, 18-month contract and slow onboarding are excessive for low volumes
Watch out: Contract length is longer than most fintech readers and setup takes weeks, not minutes; reconfirm the exact term when you get a quote
Offline transaction capture, useful for businesses in patchy-signal locations
Tailored rates become competitive at high volume (roughly £75k+/year)
Reporting and chargeback handling designed for merchants with dedicated finance teams
Promotional £0/month terminal rental currently available on the public Simplicity plan
Contract length runs longer than fintech competitors and is harder to exit early
Setup and onboarding are slower than fintech competitors, weeks, not minutes
POS integrations require direct confirmation for your specific setup
The £0/month rental is a promotion, not the standard price: confirm the end date before signing
Offline transaction capture with built-in WiFi and 4G fallback, keeps taking payments in patchy-signal locations
Next-day settlement on standard accounts
Accepts Amex alongside Visa and Mastercard
Merchant portal with reporting and chargeback handling built for dedicated finance teams
Tailored rates for businesses above roughly £75k annual card turnover
Promotional £0/month terminal rental currently available on the public Simplicity plan
How to Choose the Best Card Machine for Small Businesses
Opening a comparison with the lowest percentage is how businesses end up on the wrong machine. The figure that matters is the total monthly cost at your own turnover, average sale and card mix.
Start with Total Monthly Cost
The comparison needs three figures: monthly card turnover, average sale and the proportion of payments made with Amex, commercial or overseas cards. Those determine whether a low percentage really saves money.
A pay-as-you-go reader is usually cheapest while turnover is low or unpredictable. A monthly plan becomes more attractive once the reduction in transaction fees exceeds the subscription and any equipment rental.
Square also includes basic POS software. If another provider requires separate till software, include that subscription in the comparison rather than treating the reader as the whole system.
Check Amex and Commercial-Card Pricing
Square, SumUp pay as you go and Zettle charge the same published flat rate for Amex as for other eligible in-person cards. myPOS and Revolut charge more. Tide does not accept Amex, while Barclaycard Smartpay Anywhere is limited to Visa and Mastercard.
This matters most where customers regularly use corporate or premium cards. If you do not know your card mix, ask the current provider for a transaction report before comparing rates.
Choose the Right Connection
Square, SumUp Solo Lite, Zettle and similar readers connect to a phone or tablet. That keeps hardware costs low. A reader with its own Wi-Fi or 4G connection costs more but removes the phone from the payment process.
For a fixed counter with reliable internet, either arrangement can work. Mobile traders, events and businesses with patchy reception have more reason to pay for a self-contained terminal. Square’s offline-payment facility provides some cover, but offline transactions carry conditions and the risk of later decline.
Check Where and When the Money Arrives
myPOS settles immediately to a myPOS account, and Zettle can make funds available in PayPal within minutes. That is not the same as settlement into your normal business bank account.
Revolut, SumUp with a SumUp account, Dojo and Tyl offer next-day or next-working-day settlement under their stated arrangements. Square’s standard settlement is normally the next working day. Tide Pay As You Go and Essential take two to three working days, while Premium settles the next day.
If cash flow is tight, check the destination account, the cut-off time, weekends and any fee for accelerated payment.
Read the Contract Before Ordering Hardware
Square, SumUp, myPOS, Zettle and Revolut do not require a fixed card-machine contract. Tyl, Worldpay and TakePayments use rental or contract arrangements that can create an exit charge.
A 12-month Tyl rental at £13.99 a month represents almost £168 of remaining payments at the beginning of the term. That may be reasonable for an established shop, but it is a real commitment for a seasonal or new business.
Ask for the full contract, the initial term, the renewal basis and the cost of leaving early. A provider’s offer to buy out an existing agreement does not remove the need to understand the new one.
Match the Reader to Your Till
Square and Zettle include POS apps that can be enough for a small shop, cafe or service business. Dojo integrates with more than 450 EPOS systems and offers hospitality-specific equipment. TakePayments, Worldpay, Tyl and Barclaycard can provide a more conventional acquiring relationship.
The support model matters when card payments are essential to trading. Check whether help is available during your actual opening hours, and whether support is provided by chat, telephone or a named account manager.
Fees and Costs to Watch
Refund, chargeback, authorisation and faster-settlement charges sit outside the headline rate, which is why they are the ones businesses meet unexpectedly.
Device Cost
Phone-paired readers are the cheapest starting point: Square costs £19 plus VAT, SumUp Solo Lite £25 and Zettle £29 excluding VAT. myPOS Go 2 adds its own connection for £39.
Standalone and rental terminals cost more. Tide starts from £29 plus VAT on its Premium plan. Dojo equipment starts from £149 upfront or £15 a month, and Tyl starts at £13.99 plus VAT a month.
Compare ownership and rental over the full contract period. Buying hardware usually costs less over time, but rental may include replacement, service or a lower processing rate.
In-Person Transaction Fees
The lowest published domestic consumer-card rates are not directly comparable, because some require a monthly plan and others charge a different amount for each card type.
Revolut starts at 0.8% plus 2p but requires paid Revolut Business and current hardware. Tide charges 0.89% plus 3p on its £17.99-plus-VAT Essential plan, while Premium charges 0.69% plus 3p on a 12-month contract. myPOS charges 1.10% plus 7p for UK consumer cards, with higher rates for several others. Dojo advertises a 1.2% blended rate below £100,000 annual card turnover, with hardware separate.
Tyl charges 1.39% plus 5p for UK and European personal cards. SumUp charges 1.69% pay as you go or 0.99% on Payments Plus. Square and Zettle charge 1.75% without a monthly fee. TakePayments and Barclaycard require a quote, so compare one using your complete card mix rather than the lowest line on the rate sheet.
Online and Remote Payment Fees
Online, payment-link and manually keyed transactions often have different prices from payments taken through the terminal.
Square charges 1.4% plus 25p for UK cards paid online, 2.5% plus 25p for non-UK cards and 2.5% for manually keyed payments. SumUp charges 2.5% online. Revolut’s published online rate starts at 1% plus 2p.
If you take orders by telephone or send payment links, ask for the card-not-present rate and include it in the same cost comparison.
Monthly Fees and Contract Costs
Add the account subscription, terminal rental, software, PCI charge and minimum monthly service charge where they apply.
Dojo separates the transaction rate, hardware and optional software. Worldpay’s public offers may reduce rental for an introductory period, but the standard rental and contract remain relevant. TakePayments sets its rental and other charges in the individual quote.
Do not assume a promotional £0 rental is the long-term price. Record when the offer ends and calculate the full contract cost before signing.
Refunds, Chargebacks and Other Charges
Refund, chargeback, authorisation and faster-settlement fees are easy to miss because they sit outside the headline transaction rate.
Square charges 1% for instant settlement; standard settlement is free. For sellers not on Premium, Tide charges £2.99 plus VAT a month for next-day settlement instead of the standard two to three working days. Essential plus that add-on costs £20.98 a month, more than Premium’s £19.99 monthly price. myPOS and Zettle make money available quickly in their own accounts, although transferring it elsewhere can add a fee or a delay.
Dispute support also varies. App-led providers generally manage chargebacks through self-service tools, while traditional acquirers may provide an account manager. For a business with high-value or frequently disputed payments, that difference may be worth more than a small rate saving.
Frequently Asked Questions
What is the best card machine for a small business?
Square Reader is the best general choice for a small business with uncertain or modest card turnover. It costs £19 plus VAT, has no monthly fee or contract, charges 1.75% in person and includes a free POS app.
What is the cheapest card machine to run?
It depends on turnover, average sale and card mix. Square and SumUp are inexpensive at low volume because there is no standing charge. Tide, Dojo or SumUp Payments Plus may cost less at higher volume, once the percentage saving exceeds the subscription or equipment cost.
Do I need a contract for a card machine?
No. Square, SumUp, myPOS, Zettle and Revolut offer equipment without a fixed processing contract. Tyl, Worldpay and TakePayments use rental or contract arrangements, so check the minimum term and the exit charge.
Which card machine pays out fastest?
myPOS makes funds available immediately in a myPOS account, while Zettle can settle to PayPal within minutes. Check whether you need the money in that provider’s account or in your usual business bank account, as a further transfer may be required.
Which card machines accept Amex?
Square, SumUp, Zettle, myPOS, Revolut, Tyl and Dojo accept Amex under their relevant terms. The rate may be higher than for a UK consumer Visa or Mastercard. Tide and Barclaycard Smartpay Anywhere do not accept Amex.
Can I take card payments without Wi-Fi?
A terminal with its own mobile connection, such as myPOS Go 2 or Dojo Go Max, does not need to use your phone’s connection. Square also supports offline payments for up to 24 hours under specified conditions, but an offline payment can still be declined when the device reconnects.
How quickly will a card machine arrive?
Delivery varies by provider and hardware availability. Phone-paired readers are often available online or from retailers, while configured rental terminals may take longer. Do not promise customers card acceptance until the reader has arrived, connected and completed a test payment.
How we reviewed Best Card Machines for Small Businesses
Ranking criteria. We assessed the total cost, hardware, contract flexibility, settlement, connectivity, card acceptance and suitability for different types of small business. Cost carries the greatest weight because it applies to every payment.
Data sources. We used provider pricing, product and terms pages. Square currently lists its Reader at £19 plus VAT, a 1.75% in-person rate and standard next-day settlement. Other figures retain the page’s provider checks and stay on the site’s monthly verification cycle.
Calculations. Break-even examples state the assumed monthly turnover, average transaction value and treatment of VAT. They compare transaction and stated fixed costs; they do not assume that every customer uses the cheapest card class.
Testing basis. This is a desk-researched comparison. We have not run every device through a live shift, so we do not present claims about physical reliability, interface quality or support as first-hand findings.
Update cadence. We recheck provider pricing, contracts and equipment regularly and when a provider announces a material change. Some links are affiliate links; see our editorial policy.

 Square Reader
Top Pick
 SumUp Solo Lite
Best for Startups
 myPOS Go 2
Best for Mobile
 Revolut Reader
Best for Growing Businesses
 Tide Card Reader
Low-fee option