

Our Verdict
If your business moves money abroad most weeks, Airwallex is an easy yes: 0.5% over the mid-market rate on major currencies, fee-free payouts on local rails to 120+ countries, and batch runs up to 1,000 payees. Little else moves B2B money this cheaply at volume.
The catch is compliance friction. Strict know-your-business checks can freeze a first or unusually large transfer, and your funds are e-money safeguarded, not FSCS-protected. For rare one-off transfers you do not need this; reach for it when volume and corridors justify it.
See Airwallex pricing →Everything below explains the trade-offs in full. This page covers moving money abroad specifically; for the multi-currency business account itself, cards, FSCS/safeguarding and day-to-day banking, see our full Airwallex business account review.
Airwallex at a Glance
For a scaling UK business sending money abroad regularly, we rate Airwallex among the cheapest fast routes available; for one-off or personal-scale transfers it is the wrong tool. The figures that decide it, all of which we confirmed from airwallex.com on 5 October 2026 and the FCA register on 5 June 2026:
| Key point | Details |
|---|---|
| Provider type | FCA e-money institution (FRN 900876), not a bank |
| Best for | Regular multi-currency supplier, contractor and payroll payouts in volume |
| FX margin | 0.5% over mid-market on 11 major currencies; 1.0% on all others |
| Transfer fees | None on local rails to 120+ countries; SWIFT £10 to £20 plus intermediary fees |
| Speed | Instant to next day on major local rails; 1 to 5 days via SWIFT |
| Limits | From £1 up to about £1,000,000 per transfer; batches up to 1,000 payees |
| Reach | Send in 60+ currencies, hold and receive in 20+, and pay out to 200+ countries and regions |
| Protection | Funds safeguarded in separate bank accounts, not FSCS-protected |
| Eligibility | UK companies, LLPs, partnerships and sole traders; document list published for each |
| Verified from airwallex.com, 5 October 2026, and the FCA register, 5 June 2026. Trustpilot 2.9/5 from 2,582 reviews (5 October 2026). | |
What Is Airwallex and How Does It Work?
What this review covers: moving money abroad, not holding it. For the account itself, its plans, cards, app and the FSCS question, read our Airwallex business account review; for card payments, see the Airwallex payment processing review.
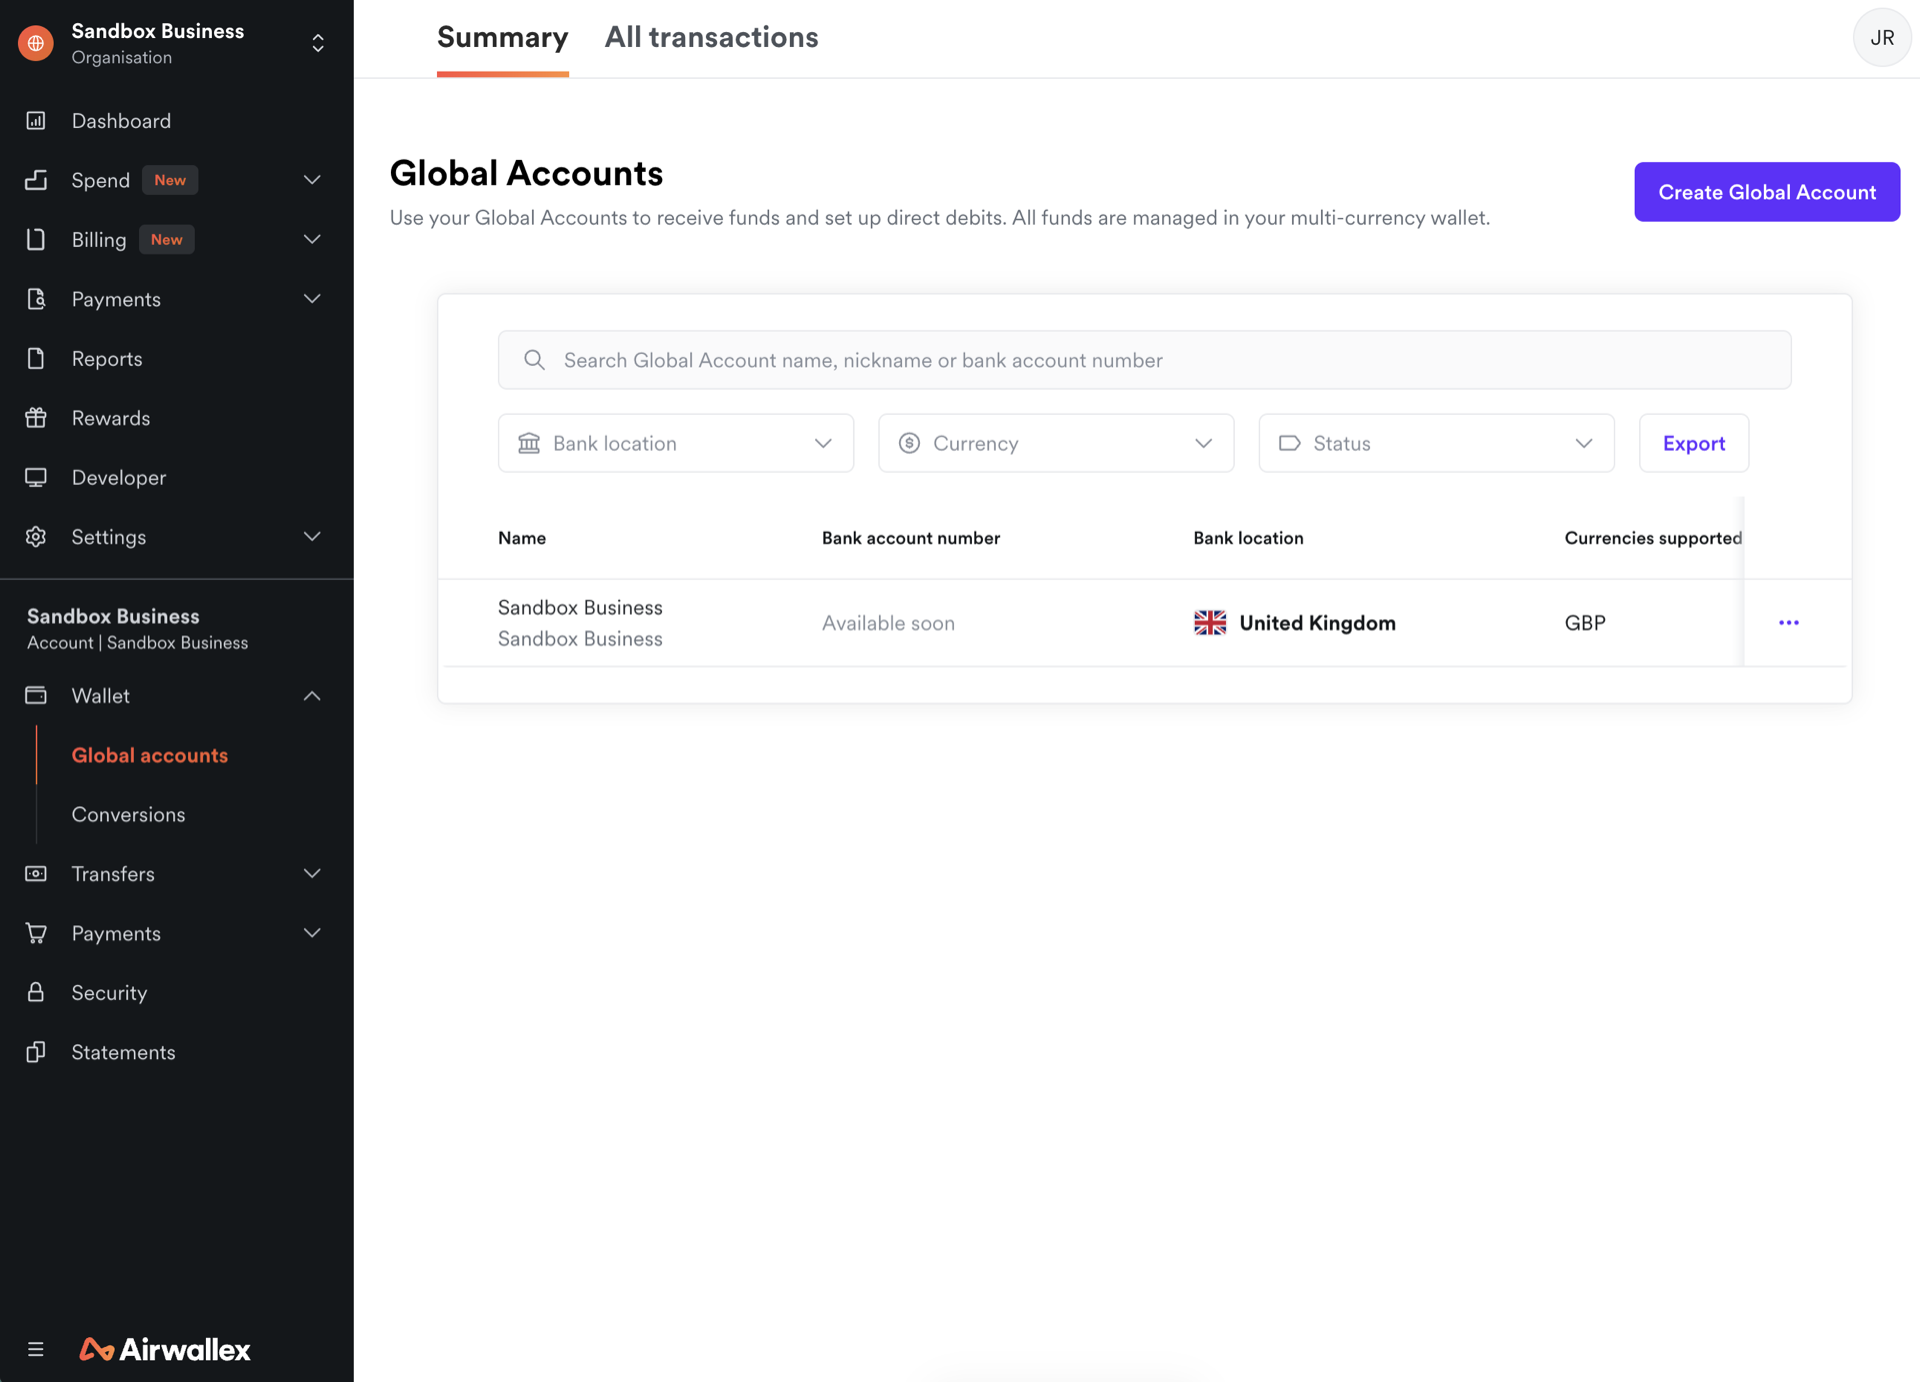
How it works: Airwallex is cross-border infrastructure, not a remittance app. It owns local bank accounts worldwide, so a payout to a supported country travels on local rails (Faster Payments, SEPA, ACH) and lands as a domestic deposit. That’s why most payouts carry no fee.
How money is delivered: for the 120+ countries Airwallex reaches locally, you pay nothing per transfer and recipients avoid intermediary deductions. Where it has no local presence, the payout falls back to SWIFT, with the fees and delays that come with it. Choosing the rail is choosing the cost.
Who it is for: you get the most from it if you move money often and in volume, holding foreign currency to convert when the rate suits. You collect through local receiving accounts, hold, then pay out, controlling the conversion point where banks take the most margin.
Exchange Rates and Transfer Fees
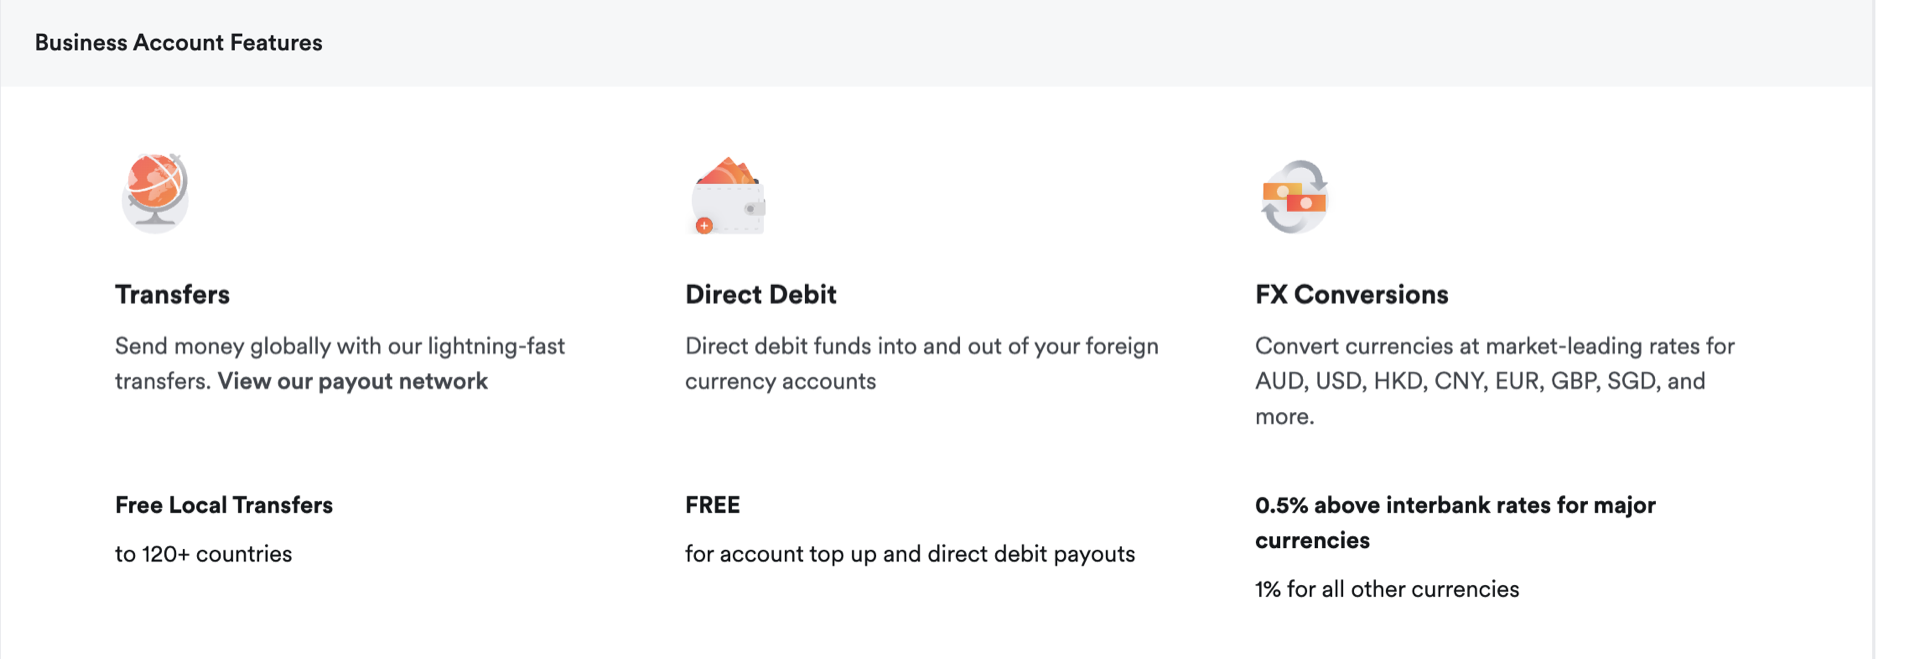
Exchange rate margin. The margin is where Airwallex wins or loses you money, and it splits in two: 0.5% over the mid-market rate on its 11 major currencies, 1.0% on everything else.
The 11 majors are USD, HKD, CNY, AUD, EUR, GBP, CAD, SGD, CHF, NZD and JPY; we verified the split on airwallex.com, 5 October 2026.
On 5 June 2026 the GBP to USD mid-market rate was 1.3432, so a £10,000 conversion at 0.5% costs about £50 in margin. The same £10,000 at a bank’s 1.5% to 2.6% costs £150 to £260. That gap is the case for Airwallex.
Watch the major-versus-other line. GBP to USD, EUR and AUD all sit at 0.5%, but GBP to INR is a 1.0% currency, double the margin, about £100 on that same £10,000. The rate does not change with transfer size on standard plans, though very high volumes can negotiate custom pricing.
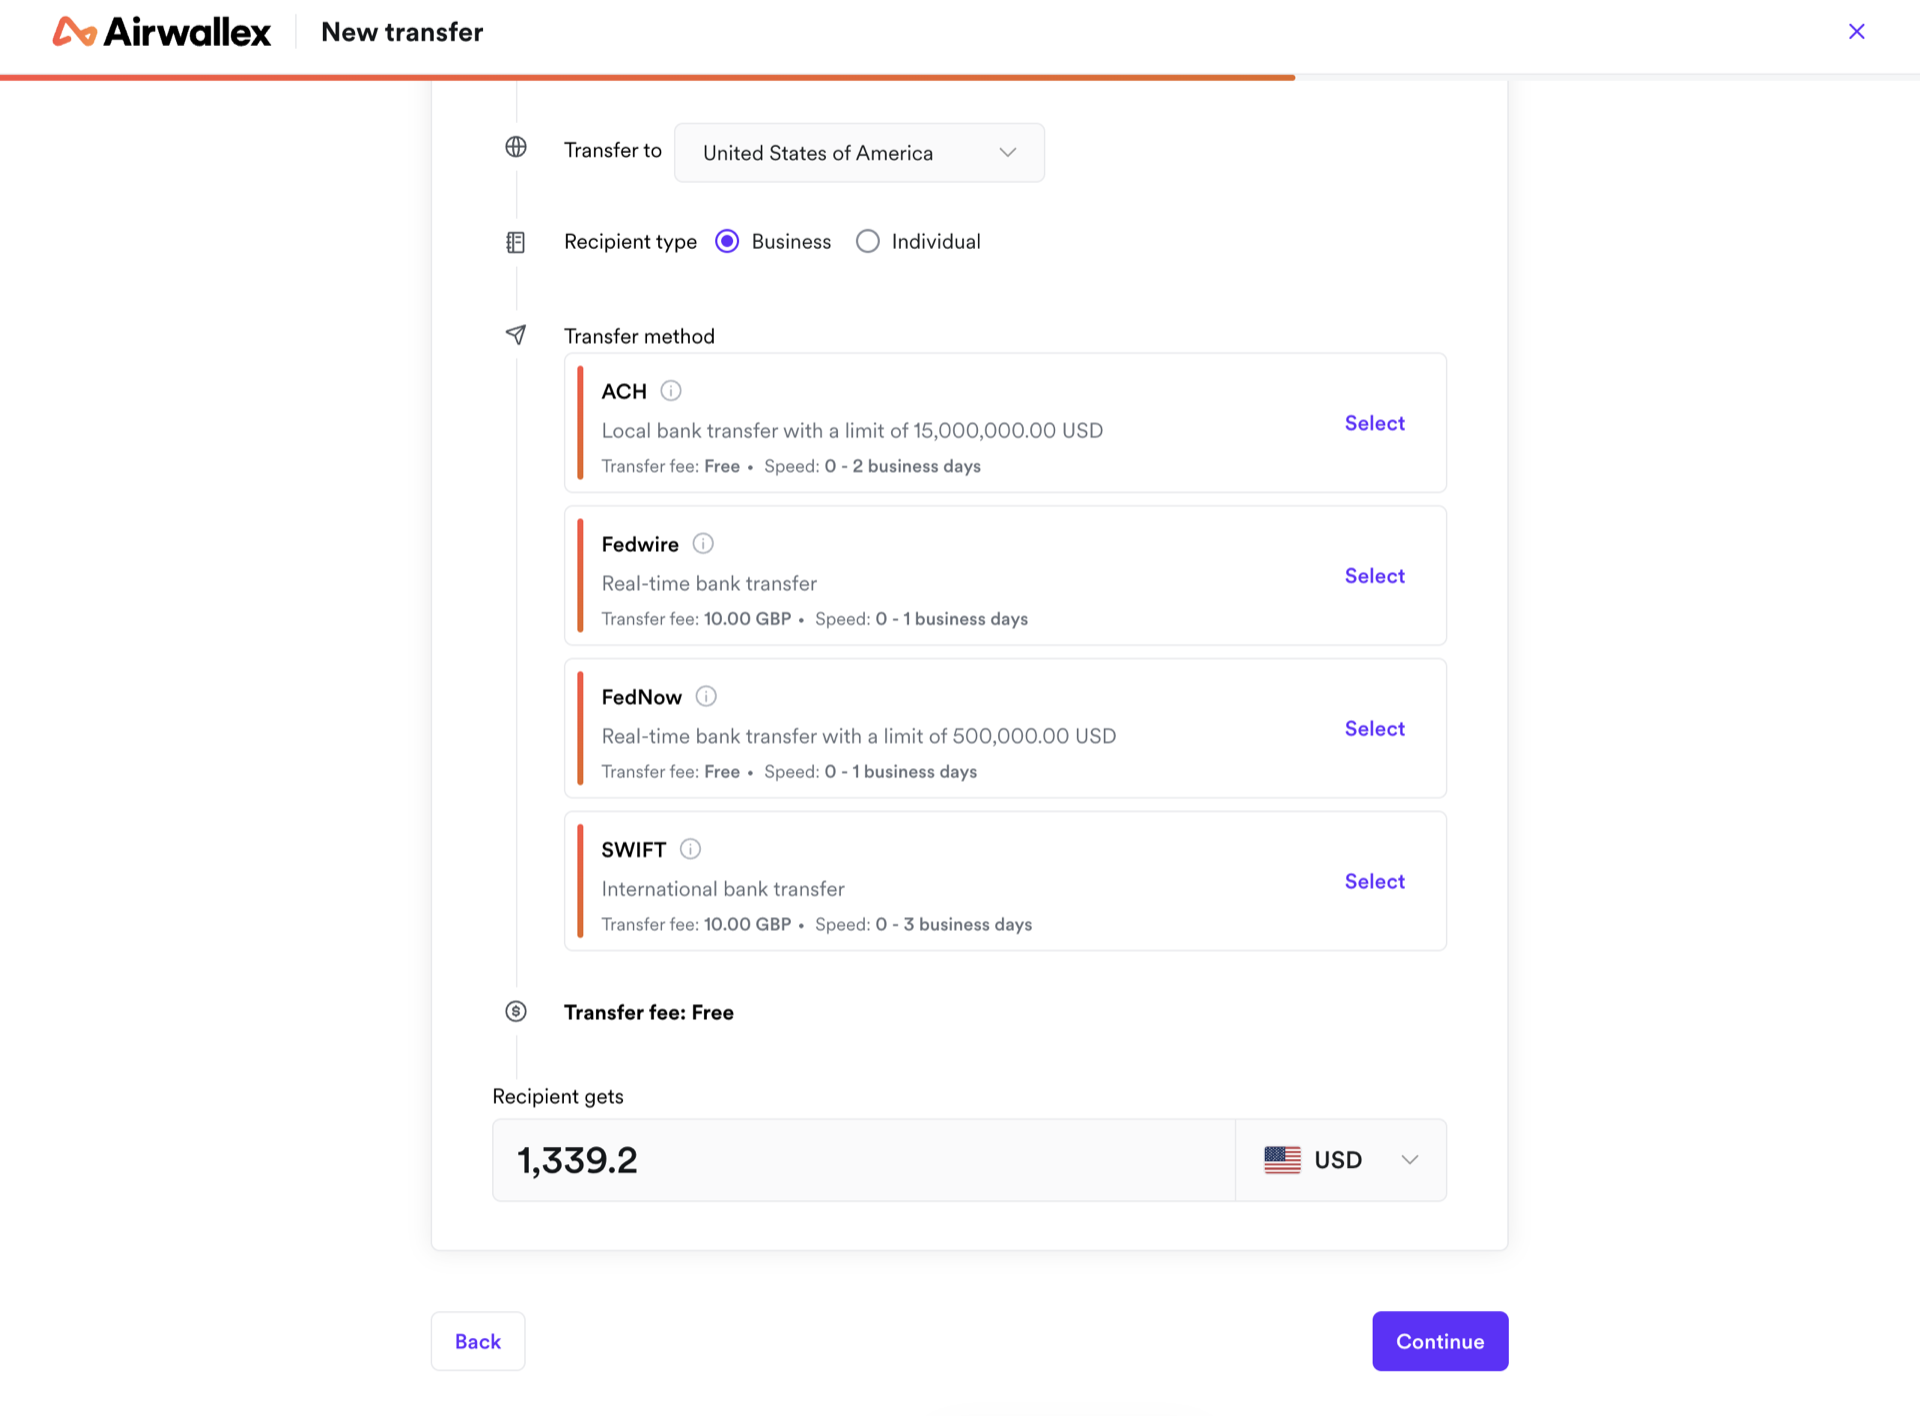
Transfer fees. The fee depends entirely on the rail, and on local rails it is zero. Pay 40 EU suppliers on a Friday over local SEPA rails and the fee line reads nothing, the same across all 120+ supported countries; Airwallex absorbs the routing cost.
That’s why you undercut a bank on regular supplier runs.
Send by SWIFT, where Airwallex has no local account, and a fixed fee of roughly £10 to £20 applies per payment. We checked both rails directly. Batching does not change this: 500 local-rail payouts still cost nothing, but every SWIFT payment in a batch carries its own fee.
| Cost | Local rails (120+ countries) | SWIFT |
|---|---|---|
| FX margin over mid-market | 0.5% major / 1.0% other | 0.5% major / 1.0% other |
| Airwallex transfer fee | None | £10–£20 |
| Intermediary bank fee | None | Varies by bank (deducted in transit) |
| Typical speed | Instant to next day | 1–5 working days |
| Verified from airwallex.com, 5 October 2026. Intermediary fees are charged by third-party banks, not Airwallex. | ||
Other costs to watch. Two costs catch you out. First, if you fund your wallet by card you pay 1.30% plus £0.20 on a UK card, up to 3.15% plus £0.20 internationally. Fund by Faster Payments or BACS instead and it’s free, so always top up from a bank.
Second, no separate conversion fee sits on top of the margin; the 0.5% to 1.0% is the whole FX cost. But the recipient’s own bank may levy an incoming-wire charge on SWIFT payments, which Airwallex cannot control. Local-rail payouts sidestep that entirely.
Transfer Speed, Limits and Payment Methods
Transfer times. Speed follows the rail. On local networks, GBP to EUR (SEPA), GBP to USD (ACH) and GBP to AUD settle instant to one business day. GBP to INR runs one to three days under stricter Indian rules, still faster than SWIFT.
Any payout that drops to SWIFT generally takes one to five business days, by Airwallex’s own guide. Even fast corridors slow down for weekend or after-hours initiation, missed currency cut-offs, and compliance holds on large or first-time transfers, so build a buffer before a hard supplier deadline.
| Corridor | Local-rail speed | FX margin |
|---|---|---|
| GBP to EUR | Instant to 1 day | 0.5% |
| GBP to USD | Instant to 1 day | 0.5% |
| GBP to AUD | Instant to 1 day | 0.5% |
| GBP to INR | 1 to 3 days | 1.0% |
| Local-rail delivery and FX margin verified from airwallex.com, 5 October 2026. SWIFT payouts generally take 1–5 business days. Speeds vary with cut-off times and compliance checks. | ||
Payment methods. You fund transfers from your Airwallex balance or by topping up the wallet. Top up free by Faster Payments or BACS bank transfer; card funding works but costs 1.30% or more, so keep it for emergencies. Payouts themselves can go to recipient bank accounts or be credited to a payee’s Airwallex wallet in your specified currency.
No cash-pickup or mobile-wallet option exists at the payout end. If a recipient cannot receive a bank deposit, Airwallex simply will not reach them, and you need a remittance specialist instead.
Minimum and maximum limits. You face effectively no minimum: you can send as little as £1, with a nominal $10 floor on standalone currency conversions. That suits micro-payments to contractors without a penalty.
At the top end, single bank transfers run to about £1,000,000 in GBP, EUR or USD, and wallet conversions default to a $5,000,000 ceiling. No published daily or monthly cap applies beyond your cleared balance, and no overdraft, so you send only what you hold.
Countries, Currencies and Payout Options
Supported countries and currencies. You can hold and convert 20+ currencies, send in 60+, and receive through local account details in 20+ (USD, EUR, GBP, AUD and more). Those receiving accounts let an overseas client pay you as a local, avoiding a forced conversion when money lands.
Payout reach is 200+ countries and regions in total, which we checked against Airwallex’s own transfers and pricing pages on 5 October 2026. More than 120 of those go via fast, fee-free local rails; the rest rely on SWIFT, at £10 to £20 a transfer and a slower arrival. Which rail your corridor sits on is what sets the deadline you can safely promise.
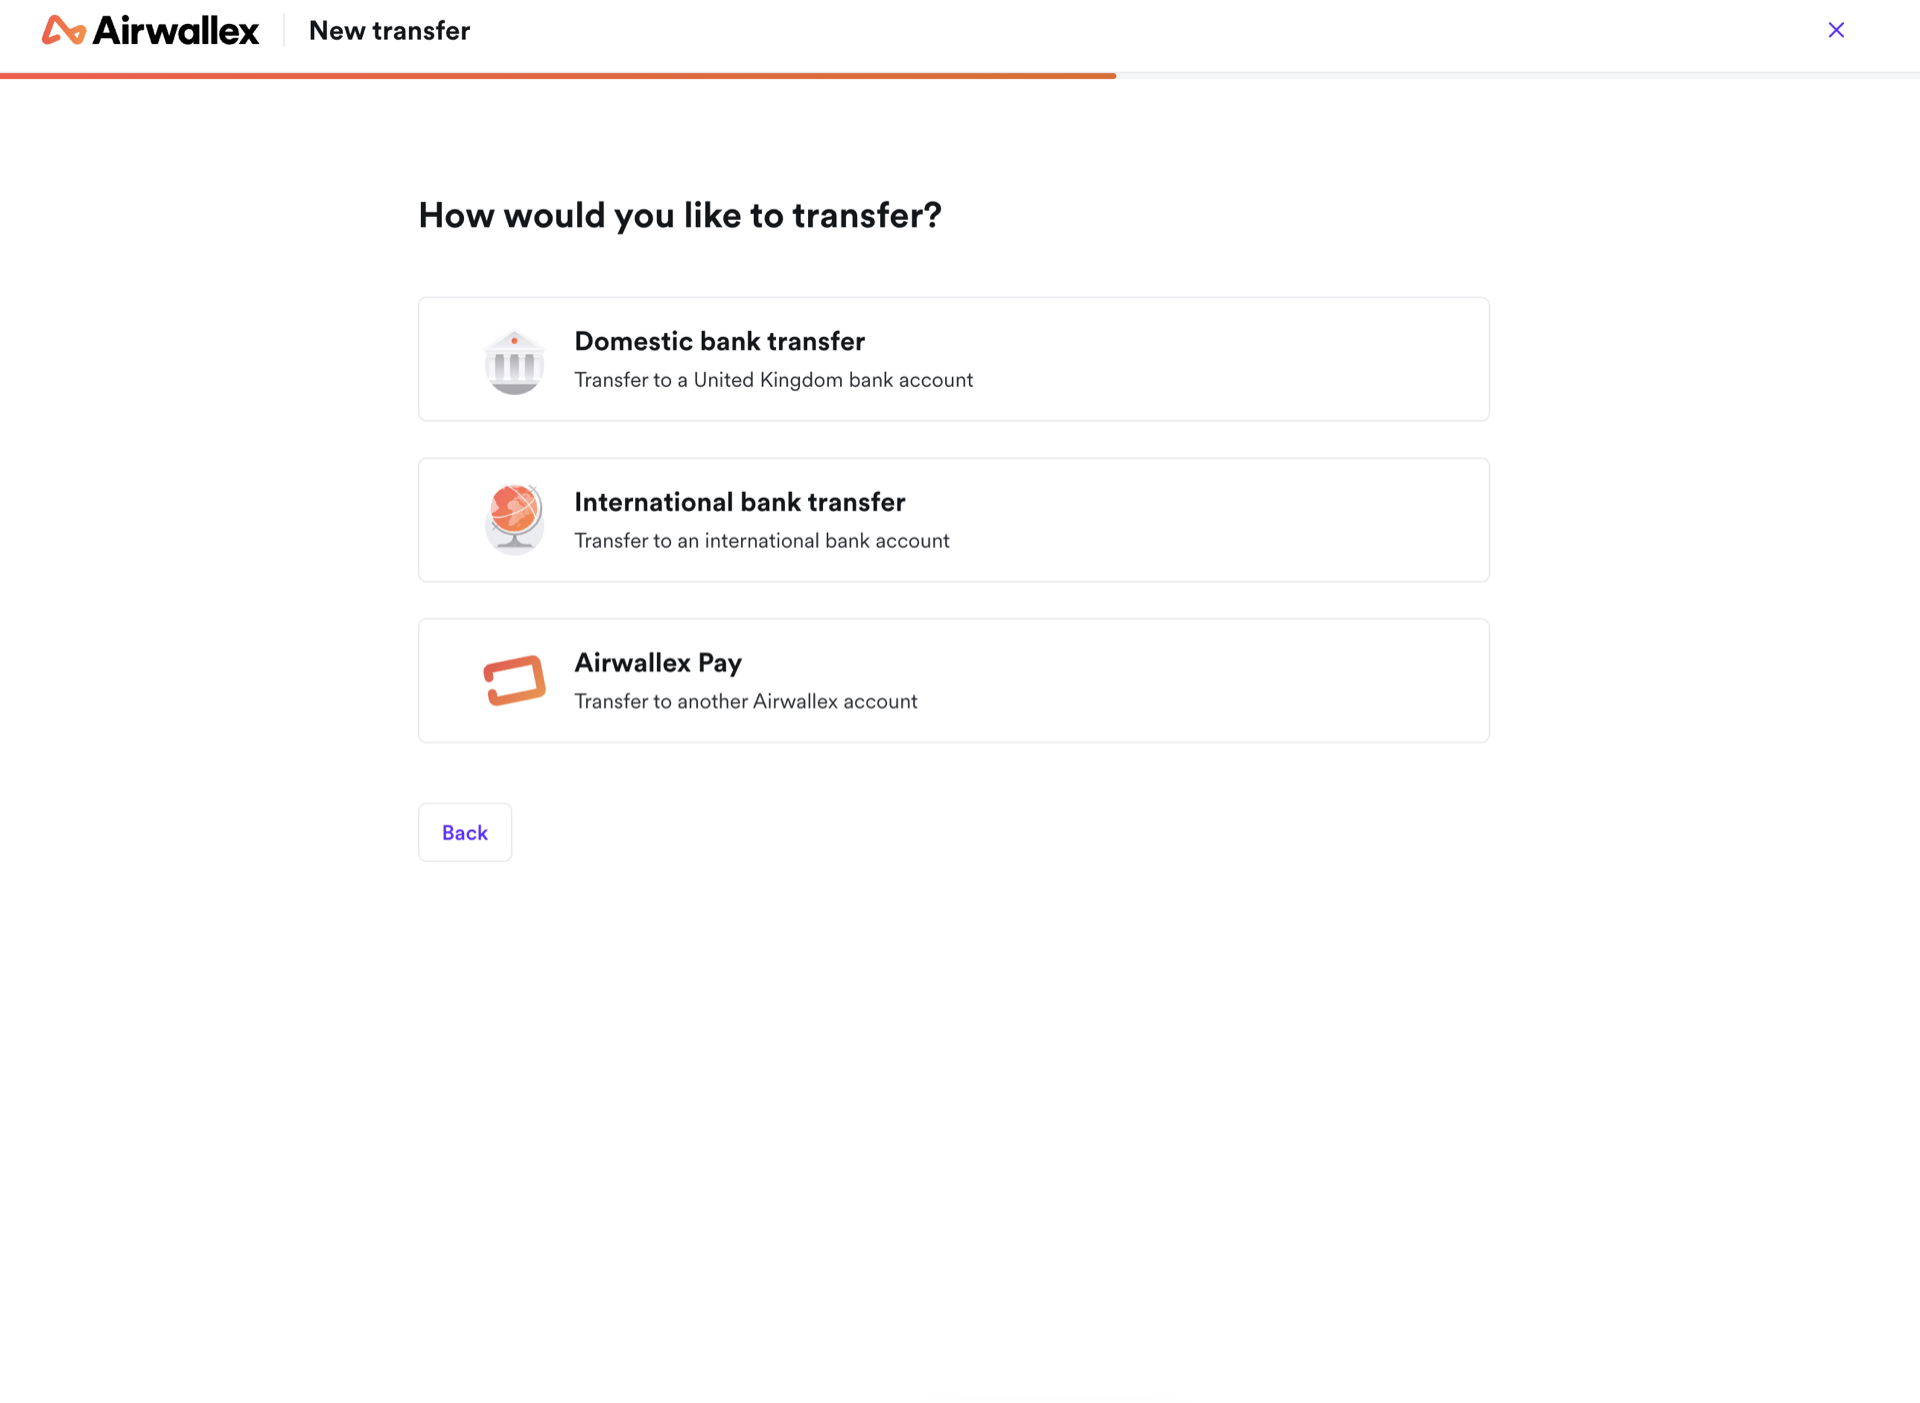
Bank, cash and Airwallex wallet payouts. Airwallex pays out to bank accounts and currently supports payouts to Airwallex wallets and PayPal. Through Airwallex Pay, it can credit funds to the payee’s Airwallex wallet in your specified currency instantly. It’s a B2B platform for institutional and corporate money movement, so there’s no cash-pickup agent network and no direct M-Pesa payout.
That’s a genuine limit, not a quibble. If you pay unbanked recipients or send to regions where cash pickup is the norm, a consumer-focused provider such as Western Union, Ria or WorldRemit will serve those recipients where Airwallex cannot.
Verification, Security and Regulation
ID and source-of-funds checks. Before you can send anything, you pass know-your-business checks: certificate of incorporation, beneficial ownership, director ID and proof of trading. Standard onboarding takes one to three business days; complex structures can stretch to weeks.
The friction doesn’t stop at onboarding. A first large transfer, an unverified third-party deposit, or a sudden spike in payment velocity can trip Airwallex’s risk models and freeze the account mid-run. Keep source-of-funds evidence ready so a request doesn’t strand a payroll deadline.
Regulation and safeguarding. Airwallex (UK) Limited is an FCA-authorised electronic money institution, FRN 900876, not a bank. We confirmed this on the FCA register on 5 June 2026. Your funds are safeguarded, not FSCS-protected, which matters if you hold real working capital.
Safeguarding means 100% of customer money sits separately from Airwallex’s own funds in separate bank accounts. If Airwallex failed, an insolvency practitioner returns it. There’s no £120,000 cap, so your balance is covered, but a return can run slower than an FSCS payout and net of admin costs.
Safeguarding is not the same as FSCS.
If statutory protection drives your decision, weigh it openly. Revolut (full UK banking licence since March 2026) and Starling pair multi-currency features with FSCS cover. Compare those if a guaranteed payout matters more than the last basis point of FX margin.
Account security. As an FCA e-money institution, Airwallex must meet the regulator’s security and operational requirements. When we opened a test account, though, account-wide two-factor authentication was switched off, including the setting that forces a check before a transfer leaves. Turning both on is the first thing to do on day one.
Airwallex publishes the shape of its controls rather than the detail: multi-user access with roles, and approval steps on payments. What it does not publish is where the thresholds sit or which roles can override them. For a finance team that needs two signatures above a set figure, that specific question is one to put in writing during onboarding.

Platform and User Experience
Website and app. The web dashboard is where a finance team lives: balances, FX conversions, payout scheduling and batch uploads. On a Monday morning you upload an Excel file of 200 contractor payments, the platform prices the FX and fees before you confirm, and the run executes in one click.
For developers, an API and webhooks let your own systems trigger payouts, create wallets and read balances directly. That automation is the real product. If your team has no developer capacity and you only send the odd payment, much of the platform’s value sits out of reach.
Customer support. You get online support, a help centre and developer docs, with dedicated account managers on higher tiers and enterprise accounts. For integration questions the documentation is strong. Airwallex does not publish which support channels each plan carries, so ask for that in writing before you commit to a tier.
Support speed is the recurring weak spot in reviews, especially outside core APAC hours. If a compliance hold lands while a time-sensitive payment run is queued, slow responses turn an admin issue into a missed deadline. Factor that into how much lead time you leave.
Customer Reviews and Reputation
What customers like. Airwallex holds 2.9/5 on Trustpilot from 2,582 reviews as of 5 October 2026; we checked this directly. Read it as two experiences, not one average. Businesses using it for its intended job rate it well above that headline.
The praise is consistent: market-leading FX rates, the speed of local-rail transfers, the elimination of double conversion through like-for-like settlement, and the efficiency of batch payouts. Enterprise users single out their account managers.
Common complaints. The negatives cluster almost entirely on compliance. Sudden account freezes, funds held without a clear explanation, and slow support responses dominate the one-star reviews. Smaller merchants find proving source of funds to unlock a frozen account heavy-handed.
Read the pattern before you commit your payroll to it. The product is excellent when it runs smoothly and painful when a risk model trips. If reliable, fast support is non-negotiable for your payment runs, weigh that against the cost saving.
The catch is the freeze risk, not the price.
Who Is Airwallex Best For?
Airwallex rewards a specific transfer profile: regular, multi-currency, bank-to-bank payouts in volume. We mapped the fit by transfer profile, not feature list. Match your use case against the table before you switch, because the gap between a great fit and a poor one is wide.
| Your transfer profile | Fit | Why |
|---|---|---|
| Ecommerce paying overseas suppliers | Strong | Fee-free local rails and like-for-like currency settlement |
| Agency paying global contractors | Strong | 1,000-payee batch payouts in one run, no per-transfer fee |
| API-driven platform embedding payouts | Strong | API and webhooks for automated transfers |
| Rare one-off international transfer | Poor | Wise is simpler, mid-market rate, and accepts sole traders |
| Paying unbanked recipients | Poor | Currently supports payouts to Airwallex and PayPal, but no cash pickup |
| High-risk sector (gambling, crypto, adult) | No | Prohibited; fails KYB at onboarding |
| Best-fit assessment based on Airwallex’s product scope and pricing, verified 5 October 2026. | ||
Airwallex Alternatives
Airwallex vs Wise
Wise gives you the true mid-market rate with no margin and a transparent fee from 0.24%, varying by currency, against Airwallex’s 0.5% to 1.0% margin. Cheaper for: small and one-off transfers, where a low fee beats a percentage margin.
Main drawback: Wise lets you create up to 1,000 payments with a single CSV or Excel file, but it has no local-rail network at Airwallex’s scale, so for high-volume, multi-corridor supplier runs Airwallex pulls ahead on both cost and automation.
Airwallex vs Revolut
Revolut Business bundles transfers into a broader spend platform and gives you the interbank rate inside your plan allowance, adding about 0.6% beyond it. Better for: mixed spend and the reassurance of FSCS protection, which Revolut gained with its full UK banking licence in March 2026.
Main drawback: meaningful FX allowances sit on the pricier paid tiers, and the 0.6% out-of-allowance margin tops Airwallex’s 0.5%. For pure high-volume payouts, Airwallex is the cheaper engine.
Full comparison: our Revolut vs Airwallex guide.
Airwallex vs WorldFirst
WorldFirst is the closest like-for-like: around 0.5% margin on major currencies, strong ecommerce focus, and 90% of transfers landing next day. Faster for: many standard corridors, where its delivery is comparable to Airwallex.
Main drawback: WorldFirst caps batch payouts at 200 payees against Airwallex’s 1,000, and lacks the same API depth. If you pay hundreds of recipients a month or automate payouts, Airwallex scales further.
Final Verdict: Is Airwallex Worth Using?
Use Airwallex if: you move money abroad most weeks and in volume, mostly on major-currency corridors, and you want the lowest realistic cost. At 0.5% over mid-market with fee-free local rails and 1,000-payee batches, it’s among the cheapest fast routes a UK business has.
Avoid Airwallex if: your transfers are rare or one-off, you pay recipients who cannot receive money through a bank account, Airwallex or PayPal, or you need FSCS deposit protection. In each of those cases the freeze risk and EMI safeguarding outweigh the saving.
Best alternative: Wise for occasional or small transfers; WorldFirst for a near-identical FX profile with a lighter batch need; Revolut if FSCS and bundled spend matter more than margin. We rate Airwallex a strong buy at volume, a poor fit for one-off senders.
Frequently Asked Questions
Does Airwallex Use the Mid-Market Exchange Rate?
Not exactly. Airwallex benchmarks against the mid-market rate but adds a margin: 0.5% on its 11 major currencies (including GBP, USD, EUR and AUD) and 1.0% on all others, such as INR. That is still well below a typical high-street bank’s 1.5% to 2.6%. We confirmed the margins on airwallex.com on 5 October 2026.
Is Airwallex Cheaper Than a Bank for Transfers?
Usually, yes, for international payouts. On local rails to 120+ countries Airwallex charges no transfer fee and 0.5% FX margin on major currencies, where a bank often charges £9.50 to £15 plus a 1.5% to 2.6% margin. On a £10,000 conversion that is roughly £50 versus £150 to £260. SWIFT payouts narrow the gap because they add fixed and intermediary fees.
How Long Does a GBP to EUR Transfer Take?
On Airwallex’s local SEPA rails, GBP to EUR payouts typically land instant to one business day, so a morning supplier payment clears the same day. GBP to USD and GBP to AUD are similar; GBP to INR runs one to three days. A payout routed via SWIFT generally takes one to five business days, and weekends, cut-off times or compliance checks add delay.
What Is the Maximum Transfer With Airwallex?
Single bank transfers run up to about £1,000,000 in GBP, EUR or USD, with higher ceilings in some currencies, and wallet currency conversions default to a $5,000,000 limit you can request to raise. No published daily or monthly cap applies beyond your available cleared balance, and no minimum worth worrying about (you can send as little as £1).
Is Airwallex Safe, and Is It FSCS-Protected?
Airwallex is authorised by the FCA as an electronic money institution (FRN 900876) and safeguards 100% of customer funds in separate bank accounts. It is not FSCS-protected, with no £120,000 guarantee. If Airwallex failed, an insolvency practitioner would return your money, with no upper cap but potentially slower than an FSCS payout and net of administration costs. Revolut and Starling offer FSCS cover if that matters more to you.
Can Sole Traders Use Airwallex for Transfers?
Yes. Airwallex’s UK help centre lists sole traders beside limited companies, LLPs and partnerships, and publishes the documents a sole trader needs: proof of business address and photo ID with a liveness check. If your transfers are occasional, Wise may still cost less, because it charges no FX margin.
How we reviewed Airwallex for transfers
What we assessed. We evaluated Airwallex purely as a money transfer route: FX margin over the mid-market rate, transfer and payout fees by rail, speed by corridor, limits, coverage and protection. Account plans, cards and card acceptance sit in our separate Airwallex reviews.
Data sources. Airwallex’s UK pricing and product pages were checked directly on 5 October 2026, alongside a live mid-market rate snapshot (GBP to USD 1.3432) and the FCA register for FRN 900876, both read on 5 June 2026. Trustpilot was read for review themes. No comparison-site summaries or affiliate material.
Update cadence. We re-verify this page when Airwallex changes pricing, corridors or terms, and at least monthly. The verification date reflects the most recent full review. Some links on this page are affiliate links; see our editorial policy.